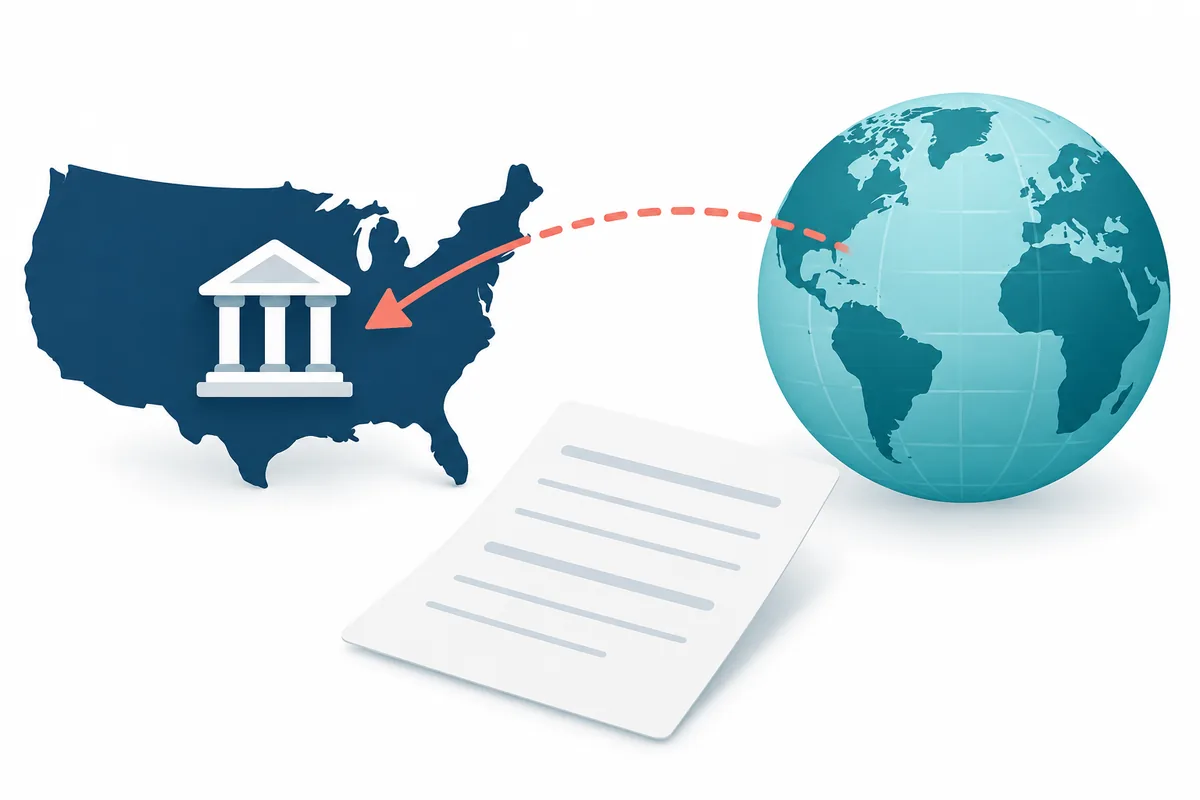
Does the US use IBAN?
No. The United States does not have a registered IBAN format for US bank accounts. When sending money to a US account, use the receiving bank's current incoming-wire instructions rather than trying to create an IBAN.
Those instructions may specify an account number, wire-specific routing details, a SWIFT/BIC, or an intermediary bank. The exact fields vary by institution, currency, and payment route.
If a form requires an IBAN for a US destination, confirm the destination country and ask the sender or provider how it supports US bank details. Do not invent or convert an account identifier.
What the answer means for a US bank account
When people ask, "Does the US use IBAN?", they are usually trying to complete a cross-border payment form. The useful distinction is where the beneficiary's account is held, not where the sender lives. A person in the United States can send money to an IBAN account abroad, but a US account holder does not receive a US IBAN to put on an incoming-payment form.
Swift maintains the registry of national IBAN formats. The United States is not listed as a country with a registered IBAN structure. Bank of America separately states that the US does not participate in IBAN and that its accounts do not have IBANs. That bank source is a clear example, not a universal list of fields for every US institution.
What US banks use instead of an IBAN
For an incoming international wire, the receiving US bank supplies instructions that identify the destination account and route the payment through the relevant banking network. The exact combination depends on the institution, the currency, the sender's bank, and any correspondent or intermediary bank involved. Ask the bank that holds the account for the current instructions for the specific payment type.
You may see several identifiers in those instructions. They are not interchangeable, and seeing one on a form does not mean every transfer needs all of them. The bank's own wire guide determines what to provide and how each field should be entered. The question "Does the US use IBAN?" is about the account's country format, not a code reconstructed from other fields.
| Detail | What it identifies | How to use it |
|---|---|---|
| US account number | The customer's account at the receiving institution. | Use the value and formatting supplied by the bank for incoming wires. |
| ABA routing number | A US bank or payment-routing destination for a particular payment path. | Use the wire-specific routing number if the bank gives one; do not assume an ACH number is the right field. |
| SWIFT/BIC | A bank or financial institution used in international payment routing. | Include it only as directed by the receiving bank; it is not an account number or an IBAN. |
| Intermediary-bank details | A correspondent institution used on some currency or route combinations. | Provide them only when the bank's instructions for that transfer call for them. |
If a payment form asks for a US IBAN
First confirm the country attached to the beneficiary's bank account. A US mailing address, business address, or sender location does not prove that the destination account is in the United States. If the account is actually held by a bank in an IBAN country, the beneficiary should obtain that account's IBAN from the bank. If the destination is a US account, do not enter a made-up value just to get past the form.
Some payment platforms collect one set of details and route a transfer through partner institutions. Ask the provider what its field accepts and whether it supports a US destination; a generic label may not match the bank's own terminology. A useful support question is: "Does the US use IBAN for this destination, or does your form need bank-issued wire details?"
If the form still requires an IBAN after you select the United States, pause before submitting. Ask the sender or provider to confirm the destination country and payment method, then compare its answer with the receiving bank's incoming-wire guide. Never paste a routing number, account number, or SWIFT/BIC into an IBAN box unless the provider explicitly documents that workflow.
How to confirm incoming-wire details
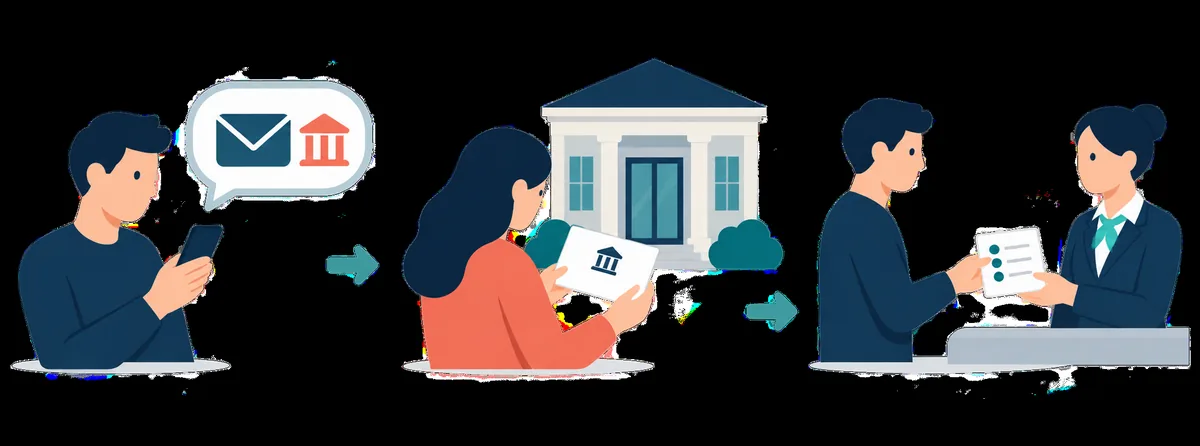
Use a source controlled by the account-holding bank: its official website, authenticated online banking, the bank's official app, or a verified support channel. Search results, old invoices, forwarded messages, and a sender's generic checklist can be useful clues, but they may be stale or intended for a different currency, branch, or payment route. If a form still leaves you asking, "Does the US use IBAN?", verify the account country before sending anything.
Before sending any details, make sure the instructions say they are for receiving an international wire into your type of account. If a business, brokerage, credit union, or fintech provider holds the account, follow that provider's own guidance; its settlement bank and the account's brand name may differ. Ask the bank which fields are mandatory, which are optional, and whether the sender must include an intermediary institution.
- Verify the destination accountConfirm the beneficiary name, the institution that actually holds the account, and the country of that account.
- Open the bank's wire instructionsChoose incoming international wires and the relevant currency or transfer method, if the bank offers separate guides.
- Match each field by nameCopy only the details requested by the sender and confirmed by the bank; do not rename or convert an identifier.
- Confirm exceptions securelyIf fields conflict or are missing, contact the bank using a verified channel before authorizing the transfer.
Mistakes to avoid when a US account is the destination
Keep the task simple: identify the account country, retrieve the bank's own instructions, and ask the sender or platform to map those instructions into its supported fields. If there is no supported way to enter US bank details, do not improvise a format. Use the provider's documented alternative or choose a payment method the receiving bank confirms it can accept.
- Do not answer "Does the US use IBAN?" by changing an account number or routing code; verify the account country and bank instructions.
- Do not append a US country code or check digits to an account or routing number.
- Do not treat an ABA routing number and a SWIFT/BIC as substitutes; they identify different routing information.
- Do not assume a domestic ACH routing number is the same as the wire-routing detail required by the bank.
- Do not rely on a format check to confirm account ownership, account status, or whether a transfer will arrive.
- Do not send full account details in an unverified email or to a person who cannot explain why the fields are needed.
Does the US Use IBAN? FAQ
Does the US use IBAN for an international wire?
No. The United States is not listed in Swift's registry as a country with an IBAN format, and Bank of America says its US accounts do not have IBANs. For a payment to a US account, obtain the receiving bank's current wire instructions.
What should I use instead of an IBAN for a US account?
There is no single replacement field for every bank or transfer. The receiving bank may provide an account number, wire-specific ABA routing information, a SWIFT/BIC, or intermediary-bank details. Follow its instructions for the exact currency and route.
Can a US bank receive an international wire without an IBAN?
Many US banks publish instructions for incoming international wires that use their own routing details. Whether a particular account, currency, or transfer path is supported is up to the bank, so confirm directly before the sender initiates payment.
Why does a transfer website require an IBAN for the United States?
The site may have the wrong destination country selected, may not support US bank details, or may use an IBAN field as part of a payment flow that needs clarification. Ask the provider what the field accepts; never invent an IBAN to satisfy validation.
Is a US routing number the same as an IBAN?
No. An ABA routing number is a US routing identifier, while an IBAN is a structured account identifier used under a registered national format. They serve different purposes and cannot be substituted by assumption.
Is a SWIFT/BIC code enough to receive an international payment?
Not necessarily. A SWIFT/BIC identifies an institution, not the customer's account. The receiving bank's instructions determine whether the sender also needs account details or an intermediary bank.
Can I convert a US account number into an IBAN?
No. There is no conversion that creates a bank-issued US IBAN. Do not use an IBAN generator or checker to invent real payment details; ask the bank for its official incoming-wire instructions.
Bottom line
Does the US use IBAN? No: US bank accounts do not have IBANs. A US account may still receive an international wire, but the receiving bank supplies the identifiers and instructions for that account and payment route.
If a form asks for a US IBAN, verify the account country, ask the sender or payment provider what its field expects, and follow the bank's current incoming-wire guide. Never create, guess, or convert an identifier for a real transfer.
Sources and further reading
- Swift IBAN Registry — Swift's reference for registered national IBAN formats and the IBAN standard.
- Bank of America: Wire Transfers FAQs — One US bank's published explanation of its incoming-wire details; requirements vary by institution.